
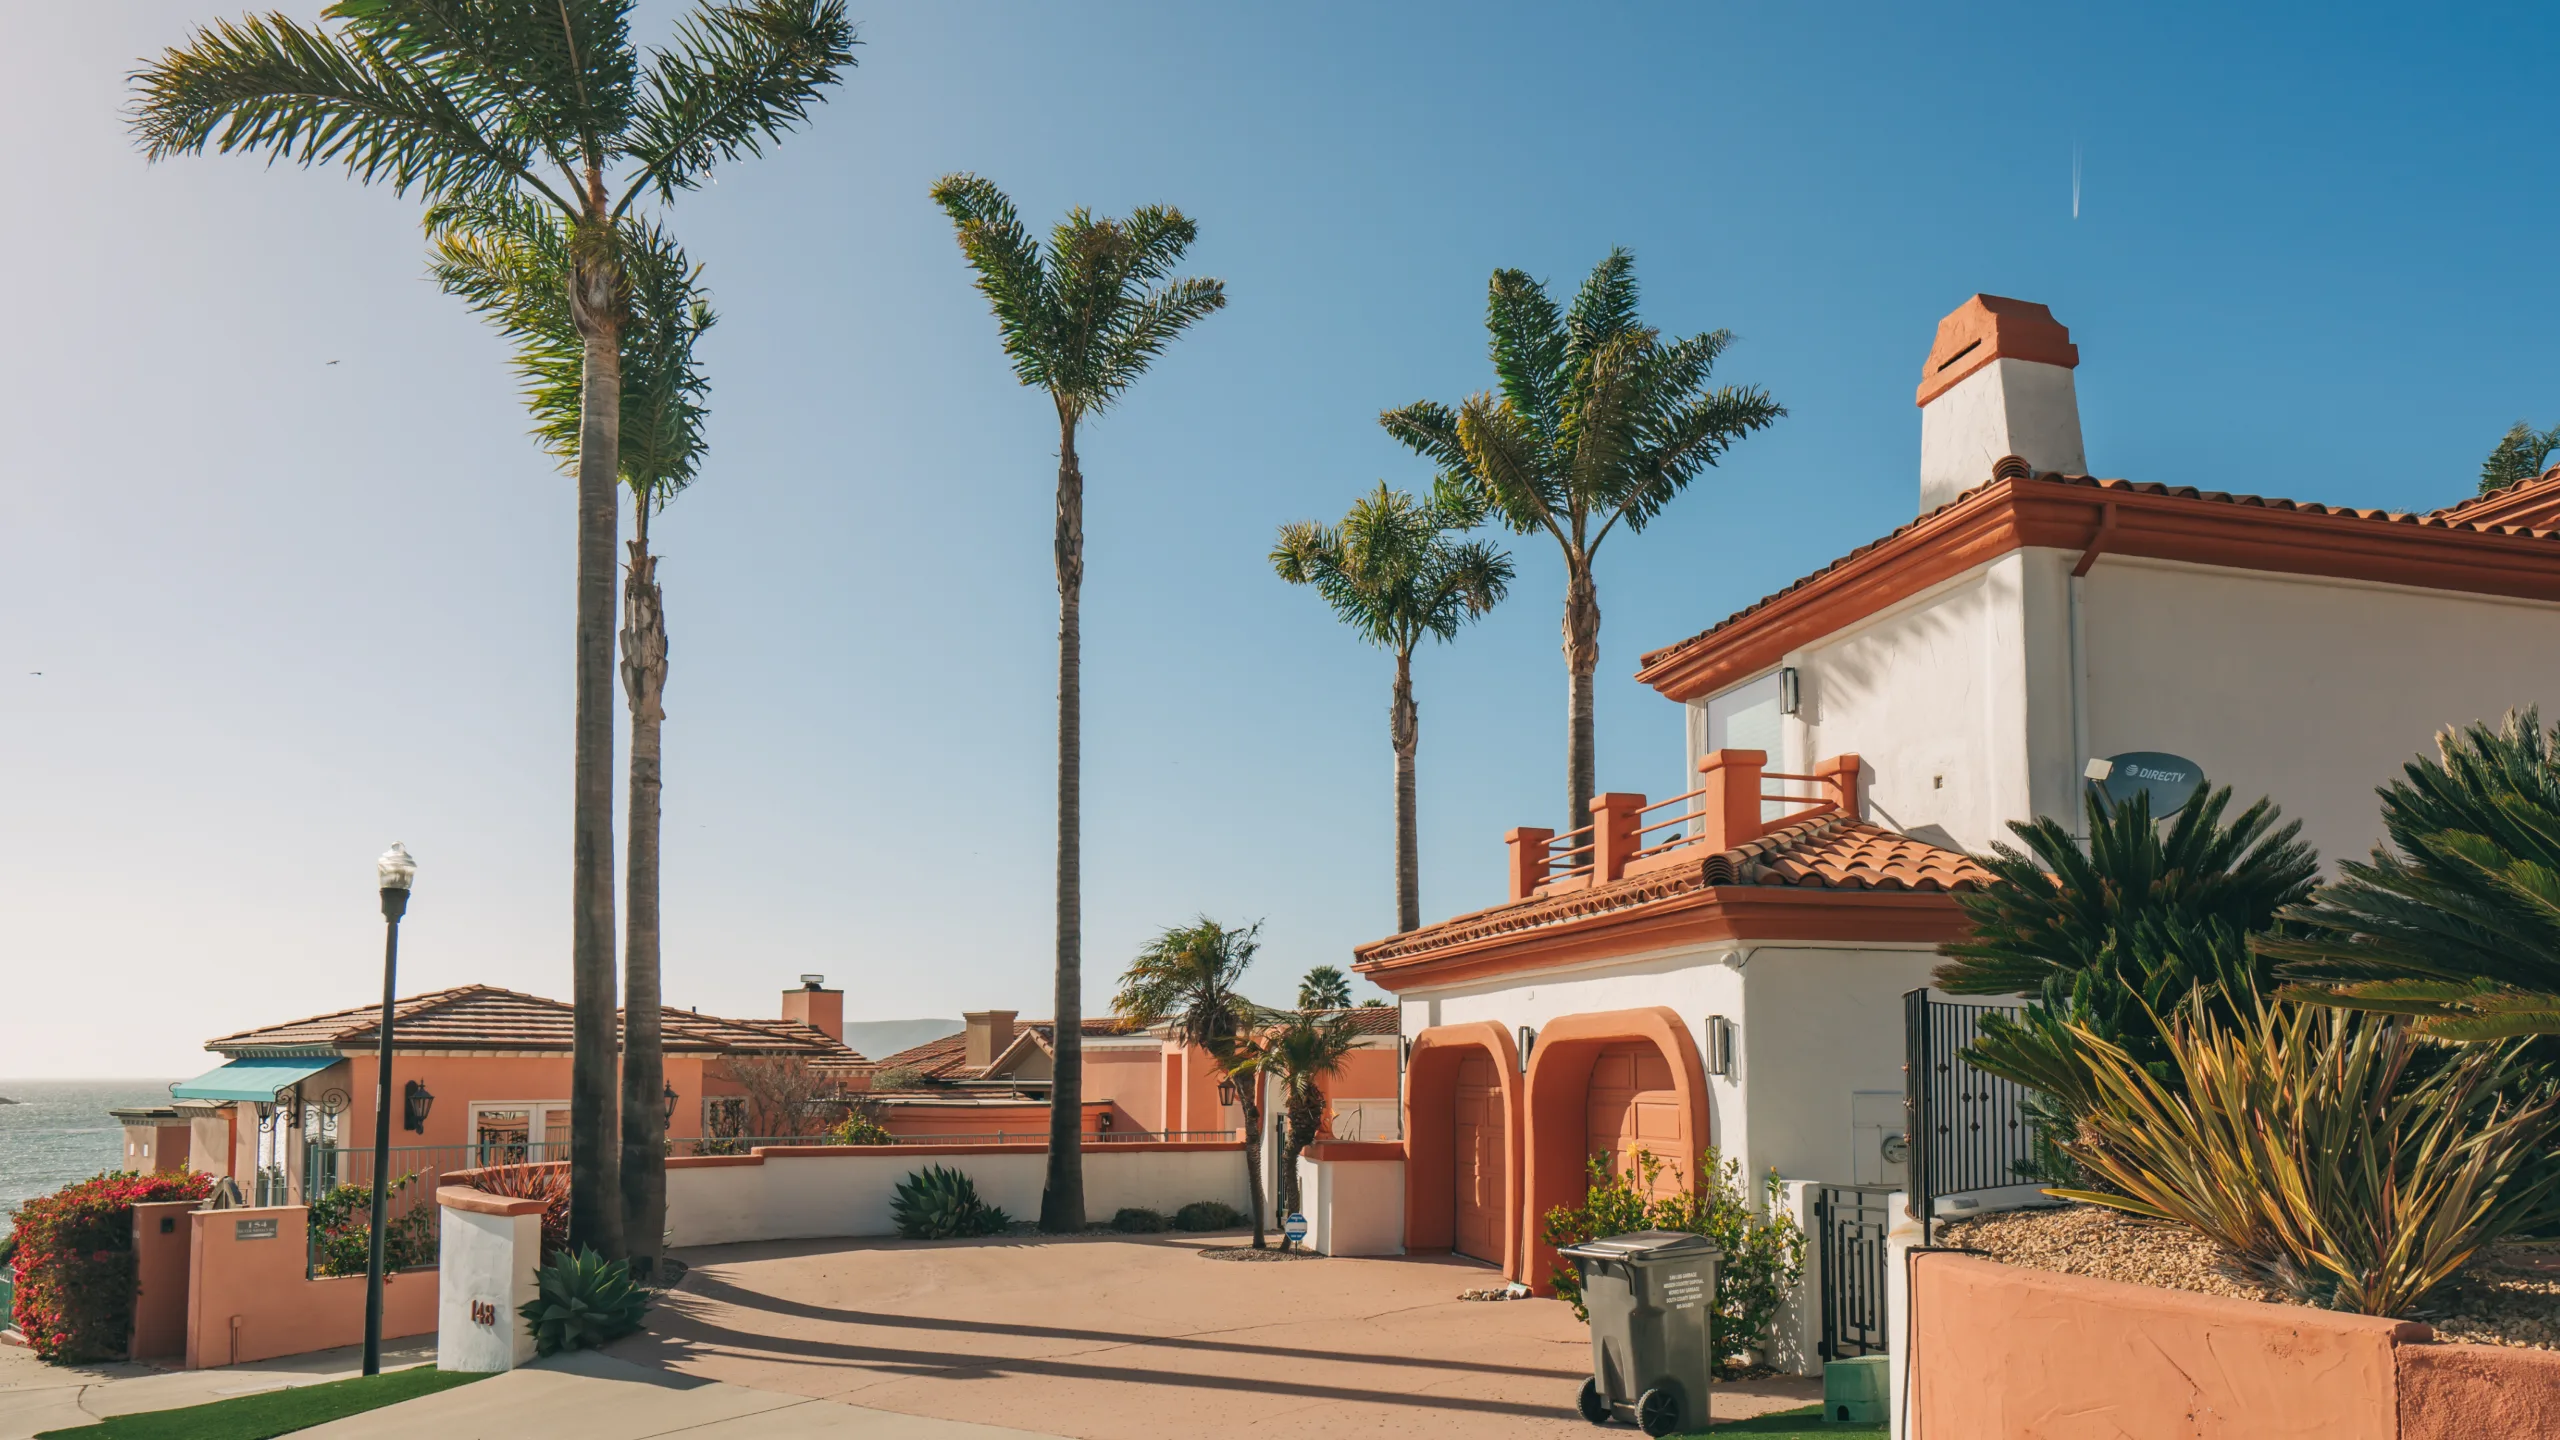
California real estate operates at a different scale. In Beverly Hills, Malibu, and across the broader Los Angeles market, a conventional conforming loan — currently capped at $832,750 in most markets, with high-balance conforming limits reaching as high as $1,249,125 in certain California counties — often does not reach the purchase price. For buyers acquiring property above those thresholds, Jumbo financing becomes the primary solution.
But is a jumbo loan a good idea for your situation? The answer depends on how well the loan is structured and whether the lender you choose can navigate complexity.
When a Jumbo Loan Becomes Necessary in California
The conforming loan limit applies to mortgages eligible for purchase by Fannie Mae and Freddie Mac. Loans exceeding that limit are classified as Jumbo loans and therefore cannot be sold through the standard Fannie/Freddie secondary market; instead, lenders either keep them in-house or sell them to private investors.
In high-cost California markets, Jumbo financing is the standard for purchases over $1M. We regularly originate Jumbo ARMs up to $25 million for qualified borrowers. If you are purchasing a luxury primary residence, a second home, or an investment property in California, a Jumbo mortgage is the mechanism that makes it possible.
Key Benefits of a Jumbo Loan in California
Flexible Underwriting for Complex Financial Profiles
One of the most significant advantages of a jumbo loan at the boutique level is that Jumbo products are underwritten by portfolio lenders and private banks — not automated systems designed for W-2 wage earners. That creates meaningful flexibility. For self-employed borrowers, entrepreneurs with NOLs, and executives with RSU compensation, Jumbo underwriting can account for the full financial narrative in ways conventional programs cannot.
Competitive Rates With the Right Structure
Jumbo rates are not automatically higher than conforming rates. In certain rate environments — particularly when the spread between portfolio lender pricing and agency pricing compresses — Jumbo ARMs can offer materially lower payments for borrowers with a defined time horizon. The key is accessing the right lender relationships and structuring the loan accordingly.
Higher Loan Limits, One Transaction
Consolidating a high-value acquisition into a single Jumbo loan avoids the complexity and cost of stacking multiple financing layers. For buyers who have the liquidity profile to qualify, one well-structured Jumbo loan is often cleaner than the alternative.
Potential Drawbacks: What Borrowers Should Anticipate
Understanding the disadvantages of a jumbo mortgage is essential before proceeding. These are not disqualifying, but they require preparation.
Stricter Documentation Requirements
Jumbo lenders operate outside the Fannie/Freddie framework, which means they set their own underwriting standards. Borrowers should expect detailed asset verification, full tax return analysis (often two years), and in some cases, third-party review of complex income structures. For complex borrowers, this is where narrative-driven underwriting becomes critical.
Reserve Requirements
Jumbo programs typically require 6–18 months of post-closing reserves, depending on loan size and lender. For a $5M loan, that can mean significant liquidity held in verified accounts. Borrowers who prefer to keep capital deployed — in equity positions, private holdings, or business operations — need to plan for this well in advance.
Rate Sensitivity
Jumbo pricing is tied closely to the 10-year Treasury yield and private lender capital costs — not the Fed Funds rate. When the 10-year moves, Jumbo ARM pricing moves with it. Borrowers who do not understand this relationship can find themselves surprised by rate environments that would have been predictable with the right guidance.
How Insignia Structures Jumbo Solutions for California Borrowers
The benefits of a jumbo loan in California are fully realized only when the loan is built correctly from the start. That means understanding the borrower’s complete financial picture — RSUs, LLCs, layered tax strategies — and selecting the right program from a deep network of private banks, portfolio lenders, and community institutions that most brokerages cannot access.
We have been originating Jumbo loans in California for over three decades. In 2025, Chris Furie ranked #4 and Damon Germanides ranked #5 in Non-QM nationally on the Scotsman Guide — a reflection of our sustained ability to close the transactions others cannot.
The jumbo loan risks that concern most borrowers — documentation complexity, reserve demands, rate exposure — are manageable with the right advisory relationship. That is precisely what we provide.
If your purchase requires Jumbo financing, connect with our team to discuss structure, timing, and what documentation to prepare.
Insignia Mortgage | NMLS #1277691 | DRE #01969620 | Equal Housing Lender
All loans subject to credit approval, minimum FICO, and reserve requirements. Rates and terms are subject to change. Interest-only loan payments do not reduce the principal balance; payments will increase once the interest-only period ends. Consult a qualified CPA or financial advisor for guidance specific to your tax and wealth planning situation.